Manchester-Based Crediflow AI Secures €1.8 Million to Automate Commercial Loan Processing: A New Chapter for AI-Powered Lending
The financial technology sector is seeing another example of artificial intelligence moving beyond chatbots and into everyday business operations. Manchester-based fintech company Crediflow AI has raised £1.5 million, approximately €1.8 million, in new funding to expand its technology for automating commercial loan processing and credit underwriting.
The funding round was led by PXN Ventures through the Northern Powerhouse Investment Fund II, with participation from Haatch and angel investors, according to a report published by Dealroom on November 3, 2026. The investment is intended to help Crediflow develop its platform, recruit engineering and product talent, and extend automation across more stages of the commercial lending process. Dealroom News+1
The announcement highlights a growing opportunity for AI in business finance. Commercial lending often involves reviewing financial statements, bank transactions, company records and supporting documents before a lender can assess a loan application. Much of this work still depends on manual data entry, spreadsheet analysis and the preparation of reports for credit committees.
Crediflow wants to make that process faster and more connected. Its platform is designed to turn complex borrower information into structured financial analysis that credit professionals can review.
The company is not positioning its technology as a replacement for human underwriters. Instead, it aims to reduce repetitive preparation work so lending teams can spend more time evaluating risk, understanding businesses and making responsible decisions.
The Funding Round: Who Is Backing Crediflow AI?
The reported £1.5 million funding round represents an important milestone for Crediflow AI as it looks to expand its commercial lending technology.
The investment was led by PXN Ventures through the Northern Powerhouse Investment Fund II. Haatch and several angel investors also participated.
The Northern Powerhouse Investment Fund II supports businesses across the North of England by providing access to finance for companies seeking to grow, innovate and create employment opportunities.
For Crediflow, the funding comes at a time when financial institutions are increasingly exploring ways to introduce artificial intelligence into established lending operations.
The company plans to use the capital to strengthen its technology, recruit engineers and product specialists, and expand the platform beyond existing underwriting workflows.
Its longer-term ambition is to support more stages of commercial lending, including loan origination and continuous portfolio monitoring. Dealroom News+1
The round also follows earlier backing through PXN’s PraeSeed programme, which Dealroom says was supported by the British Business Bank. This earlier support helped the business move towards developing and commercialising its technology.
The new funding is therefore not simply an investment in another financial software product. It is a bet on the possibility that AI can remove some of the most time-consuming tasks in commercial credit operations.
Why Commercial Loan Processing Needs Automation
Commercial lending plays a major role in the economy. Businesses borrow money to purchase equipment, expand operations, acquire property, finance inventory and manage working capital.
Before approving a commercial loan, lenders need to understand the financial position of the borrowing business.
This process can involve examining annual accounts, management accounts, tax returns, bank statements, cash-flow reports, debt schedules and other supporting documents.
Credit analysts must collect this information, check its accuracy, organise it into standard formats and evaluate the company’s ability to repay its borrowing.
Although financial institutions have adopted digital systems, many commercial lending activities still involve spreadsheets, document transfers and repeated manual checks.
The challenge becomes more complicated when borrowers submit documents in different formats or use different accounting conventions.
A lender may receive a PDF containing annual accounts, an Excel workbook showing management figures and several months of bank statements. Analysts then need to compare the information and prepare a consistent financial picture.
This takes time and creates opportunities for mistakes.
Crediflow’s technology is designed to address this problem by connecting document collection, financial data extraction, analysis and credit reporting within a more integrated workflow. Crediflow AI+1
Meet Founder Drey Kenfack: Experience Behind the Business
The company was founded by Drey Kenfack, whose professional background includes senior credit roles at Ford Credit Bank and DF Capital Bank, according to Dealroom’s funding report.
This experience is relevant because commercial lending is a specialised field. Understanding the difficulties faced by credit teams requires more than general knowledge of artificial intelligence or software development.
Lending professionals must work with financial statements, repayment structures, cash-flow forecasts, collateral information, borrower performance and internal credit policies.
They also need to prepare documentation that can withstand review by senior managers, risk departments and credit committees.
The problem Crediflow is addressing is familiar to professionals who have spent years working with these processes: experienced analysts can spend a substantial amount of their working day preparing information instead of evaluating the underlying credit risk.
Kenfack has described manual preparation as a factor that affects how much business a lender can process and which transactions it can pursue. Dealroom News
The company’s wider team also emphasises combined experience in commercial finance, corporate finance, artificial intelligence and machine learning. Crediflow says its team has more than 30 years of combined commercial and corporate finance experience and more than 20 years of AI and machine-learning expertise. Crediflow AI
This combination of industry knowledge and technical development is central to its approach.
How Crediflow AI Automates the Lending Workflow
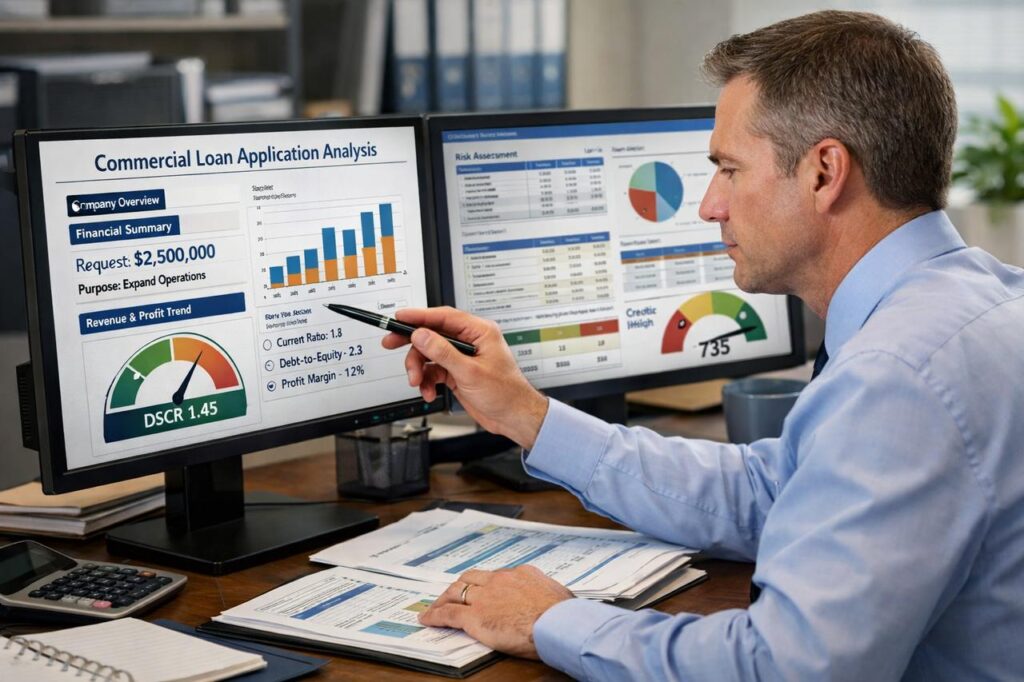
Crediflow is building an AI platform that turns borrower information into structured credit intelligence.
Instead of treating each document as a separate task, the platform is designed to connect multiple stages of the lending process.
The workflow can be understood through several important activities.
Document collection and processing
A commercial loan application may contain dozens of files. The platform is designed to help collect and process documents such as financial statements, tax returns, bank records and supporting reports.
Financial data extraction
The next stage involves identifying important figures within those documents. These may include revenue, operating expenses, assets, liabilities, cash balances and debt obligations.
Financial standardisation
Different businesses may present financial information in different formats. The system aims to organise the extracted figures into a consistent structure that lenders can use.
Cash-flow analysis
Understanding the movement of money through a business is essential for assessing its financial health. Bank statement analysis can help identify income patterns, recurring expenses and potential warning signs.
Credit memo preparation
Once the information has been collected and analysed, the platform can help prepare structured reports for lending professionals and credit committees.
Ongoing monitoring
The lending relationship does not end when a loan is approved. Lenders must continue monitoring borrowers, financial performance and potential changes in risk.
Crediflow’s ambition is to connect these activities rather than leave them scattered across disconnected systems. Crediflow AI+2
FlowSpread: Reducing Manual Financial Data Entry
One of Crediflow’s important products is FlowSpread, a tool designed to automate financial spreading.
Financial spreading is the process of extracting information from financial documents and placing it into a standardised format for credit analysis.
For example, an analyst reviewing a business loan application may need to transfer revenue, operating profit, total debt and cash balances from several financial statements into a lender’s spreadsheet model.
The figures then need to be checked and compared across reporting periods.
This is an important task because credit analysis depends on accurate and consistent financial information.
Crediflow announced FlowSpread in May 2026. The company said the system could process PDFs, Excel workbooks, tax returns and scanned documents, extract financial information and map it into a lender’s preferred credit template.
It also described a source-linking feature that connects extracted figures to their original locations in the source documents. This is intended to make verification and auditing easier. Crediflow AI
The company reported that one implementation reduced document-processing time from approximately 5.5 hours to five minutes per application, with extraction error rates below 0.1%.
These are company-reported results, not an independently verified industry-wide performance guarantee. Nevertheless, they illustrate the kind of efficiency Crediflow is seeking to deliver.
Flow Bank Statement: Turning Transactions Into Cash-Flow Intelligence
Bank statements can provide useful information about how a business operates.
They show incoming payments, outgoing transfers, loan repayments, supplier costs and other financial transactions.
However, reviewing large volumes of bank statement data manually can be time-consuming.
An analyst may need to identify recurring payments, compare deposits, understand seasonal changes and investigate unusual transactions.
Crediflow’s bank statement analysis product is designed to help automate this work.
The company describes the system as a way to convert raw PDF bank statements into structured data that can support commercial credit assessment.
This could help lenders understand cash-flow behaviour without requiring analysts to manually enter every transaction into spreadsheets.
The platform can potentially assist with identifying patterns such as:
- Regular income from customers.
- Recurring operating expenses.
- Loan repayments and other debt commitments.
- Changes in account balances.
- Unusual or inconsistent transaction patterns.
- Potential cash-flow pressures.
These observations can help credit teams decide which areas require additional investigation.
However, transaction patterns should not be treated as a complete picture of a company’s financial condition. Analysts still need to consider business context, accounting information, borrower explanations and other evidence.
Flow Credit Memo: Automating the Paperwork Behind Credit Decisions
Another product in Crediflow’s growing platform is Flow Credit Memo, launched in October 2026.
A credit memo is an important document in commercial lending. It summarises a proposed loan, the borrower’s financial position, the purpose of the funding, the risks involved and the reasons supporting the lending recommendation.
Credit committees use these documents when reviewing transactions.
Preparing a credit memo can involve transferring information from financial analysis, borrower documentation and internal reports into an institution’s preferred template.
Different lenders may have different document structures, approval sections and reporting requirements.
Crediflow says Flow Credit Memo allows lenders to upload their existing Word templates. The system then uses the template to prepare a structured credit paper containing financial analysis, tables, charts and supporting information.
The company says the system also includes source traceability, helping reviewers connect the information in a credit memo with the documents used to prepare it. Finance Connect+1
This is important because automation must not simply produce attractive documents. Credit professionals need to understand where the figures came from and whether the information has been interpreted correctly.
A well-designed credit memo tool can reduce repetitive formatting work while preserving the institution’s review process.
From Days to Minutes: What Does the Efficiency Claim Mean?
One of the most attention-grabbing details in the funding announcement is Crediflow’s claim that tasks that previously took days can now be completed in approximately 10 to 30 minutes.
According to Dealroom, the platform collects borrower documents, standardises financial data, analyses cash flow and drafts credit memos using each lender’s format. Dealroom News
This should not be interpreted as a promise that every commercial loan can be fully approved within 10 minutes.
Commercial lending involves several different stages. Some are repetitive and suitable for automation, while others require professional judgement, borrower discussions, legal checks and formal approval.
The claimed time reduction relates to preparing and processing information rather than removing every step of the lending decision.
For lenders, this distinction matters.
A faster workflow can help analysts review more applications, but the organisation must still make sure that the information is accurate and the loan meets its credit policy.
The most valuable outcome may be giving experienced employees more time to focus on difficult transactions instead of repeatedly transferring figures between documents.
Why Human Underwriters Still Matter
The growth of AI in financial services sometimes raises concerns about whether technology will replace professional employees.
Crediflow’s positioning is different. Dealroom reports that the platform does not make lending decisions or replace underwriters. Instead, it prepares the analysis that credit professionals use. Dealroom News
This is an important distinction.
A commercial loan decision may involve questions that cannot be answered by simply extracting financial figures.
For example:
- Is a temporary fall in revenue caused by seasonal trading?
- Does the business have a credible plan for expansion?
- Are unusual expenses genuinely one-off costs?
- Is the borrower overly dependent on a small number of customers?
- Does the proposed loan structure match the company’s cash-flow profile?
- Are there risks that are not visible in the financial statements?
These questions require context and judgement.
AI can help identify relevant information, compare figures and prepare analysis, but human professionals remain responsible for evaluating the wider circumstances.
The strongest approach is likely to combine automation with clear accountability.
How AI Could Help Small and Medium-Sized Businesses Access Finance
Small and medium-sized businesses often need external finance to support growth.
A company may want to purchase new equipment, expand its warehouse, hire employees or enter a new market. Access to a suitable loan can make these plans possible.
However, commercial lending can be a lengthy process.
Borrowers must provide financial information, respond to requests for additional documents and wait while lenders assess their applications.
Delays can create problems when businesses need funding to act on an opportunity.
AI-powered processing tools could help lenders organise borrower information more quickly.
If analysts spend less time collecting and standardising documents, they may be able to review applications more efficiently.
This could help financial institutions improve their operational capacity.
It does not automatically mean that more businesses will receive loans. Creditworthiness, affordability, lending policy and economic conditions will continue to influence approval decisions.
But faster preparation could make the application process more efficient for both borrowers and lenders.
The Role of Data Accuracy in AI-Powered Lending
Speed is valuable only when the information being processed is reliable.
Commercial lending decisions can have significant financial consequences. Incorrect figures or missing information could affect a lender’s assessment of repayment capacity and risk.
For example, if a business’s liabilities are incorrectly extracted from a financial statement, its financial position may appear stronger than it really is.
Likewise, if a recurring cash-flow problem is overlooked, a lender could underestimate the risk associated with a proposed loan.
This is why source traceability is important.
Crediflow’s FlowSpread announcement describes a system in which extracted data points are linked back to their locations in the original documents. Crediflow AI
Such a feature can help analysts check the source of a figure rather than relying entirely on an automated output.
A responsible AI lending workflow should also include:
- Checks for missing or inconsistent information.
- Clear records of document sources.
- Validation of extracted figures.
- Human review of unusual cases.
- Access controls for confidential borrower data.
- Monitoring for changes in model performance.
- Audit trails showing how information was processed.
These controls are necessary if automation is to become a dependable part of financial operations.
The Importance of Security and Compliance
Financial institutions handle sensitive information, including bank statements, tax records, business accounts and personal details.
Any technology processing these documents must be evaluated carefully.
Lenders need to understand how borrower data is stored, who can access it, how long it is retained and whether it is shared with external service providers.
They must also consider applicable financial regulations and internal information-security requirements.
Crediflow presents its platform as technology built for commercial lenders and credit teams, but individual institutions will need to complete their own vendor assessments before using it with confidential borrower information. Crediflow AI+1
Important questions include whether the provider supports appropriate encryption, role-based permissions, data retention controls, audit logging and incident response procedures.
AI systems also need controls against incorrect outputs and inappropriate use.
A financial institution should not assume that an automated report is accurate simply because it was generated quickly.
The output should be checked against the source evidence and reviewed according to the lender’s established policies.
Crediflow’s Existing Customers and Market Adoption
A promising technology needs customers who are willing to use it in real business environments.
Dealroom reports that hundreds of credit professionals across the UK, Europe and the United States already use Crediflow’s platform.
It also identifies specialist lenders such as AddWorking Capital and finance providers such as Iveco Capital among organisations using the technology. Dealroom News
This is an important part of the company’s growth story.
Commercial lenders are often cautious when introducing new technology because their operations involve financial risk, regulatory expectations and established internal procedures.
A platform must demonstrate that it can fit into existing workflows rather than simply offer an impressive product demonstration.
The ability to support different lender templates and document formats may be particularly relevant in this market.
Each institution may have its own credit policies, financial models and reporting requirements.
Technology that can adapt to those differences could be more attractive than software that forces every lender to follow exactly the same process.
Why the UK Is an Important Market for Financial Technology
The United Kingdom has a well-established financial services industry and an active fintech ecosystem.
London remains a major financial centre, while cities such as Manchester, Leeds, Edinburgh and Birmingham also contribute to the country’s technology and financial services sectors.
Manchester has developed a growing technology community, supported by universities, business networks, investors and companies working across software, cybersecurity, artificial intelligence and financial services.
Crediflow’s reported funding round adds another example of a northern UK fintech company attracting investment for a specialised technology product.
The Northern Powerhouse Investment Fund II is particularly relevant because it aims to improve access to finance for businesses across the North of England.
For regional startups, investment can provide more than money. It can help companies recruit employees, establish commercial relationships and build products that compete in wider markets.
Crediflow’s focus on commercial lending also gives it an opportunity to address a specific financial services challenge rather than competing across every area of fintech.
The Competitive Landscape for AI Lending Technology
Crediflow is entering a market where banks, fintech startups and established software companies are exploring AI-driven lending operations.
The broader industry is interested in reducing the time required to process applications, analyse financial information and prepare decisions.
Dealroom’s report notes that other businesses, including Nivo, and larger financial institutions such as Deutsche Bank are pursuing related efficiency improvements. Dealroom News
Competition is likely to increase as more organisations recognise the value of automating document-heavy workflows.
To stand out, Crediflow will need to demonstrate several things.
Reliable performance: The platform must produce accurate results across different types of financial documents.
Integration: Lenders need technology that works with their existing systems and processes.
Explainability: Analysts should be able to understand where figures and conclusions came from.
Security: Borrower information must be handled responsibly.
Scalability: The system must work effectively as transaction volumes increase.
Commercial value: Customers need to see measurable benefits that justify the cost of adopting the platform.
The funding gives Crediflow additional resources to develop its offering, but long-term success will depend on how well it meets these requirements.
How the New Funding Could Shape Crediflow’s Next Stage
The company has indicated that the investment will support product development, recruitment and expansion into additional parts of the lending lifecycle.
This creates several possible areas of development.
Expanding loan origination automation
Loan origination begins when a business applies for financing. It includes gathering information, collecting documents, organising applications and preparing cases for assessment.
Automation across this stage could help lenders reduce delays before underwriting even begins.
Improving portfolio monitoring
After a loan has been approved, lenders need to monitor the borrower throughout the life of the facility.
This may involve reviewing financial statements, checking covenant compliance and identifying signs of changing risk.
More connected monitoring tools could help lenders identify issues earlier.
Developing the engineering team
Hiring engineers and product specialists could help Crediflow improve its technology, develop integrations and respond to customer requirements.
Strengthening enterprise capabilities
Large financial institutions often require specific security, reporting, permissions and workflow features.
Product development may therefore need to focus on enterprise-level requirements as well as core AI performance.
These plans suggest that Crediflow wants to build a broader commercial credit infrastructure rather than remain a single-purpose document-processing tool. Dealroom News+1
What This Means for Banks and Specialist Lenders
For banks and specialist lenders, the funding news is another sign that AI tools are becoming increasingly focused on practical operational challenges.
The biggest opportunity may not be replacing the entire lending process with an automated system.
Instead, it may involve improving individual tasks that currently consume significant employee time.
A lender could use AI to collect documents, extract financial data and prepare a first draft of a credit memo. A credit analyst could then review the output, investigate unusual information and make a recommendation.
This division of responsibilities could improve productivity while preserving professional oversight.
It may also help lenders manage periods of high application volume without requiring every additional transaction to create an equivalent increase in manual administrative work.
However, lenders must evaluate whether automation genuinely improves their operations.
A successful implementation should measure processing time, error rates, analyst workload, review quality and customer experience.
The objective should be better lending operations, not automation for its own sake.
Challenges Crediflow AI Must Overcome
Although the funding round represents progress, Crediflow still faces challenges common to early-stage fintech companies.
Building trust with lenders
Financial institutions need confidence that a new technology provider can protect sensitive data and deliver reliable results.
Handling complex documents
Commercial borrowers operate across different industries and countries. Their financial documents may vary in language, format, accounting standards and level of detail.
Managing AI errors
Even sophisticated AI systems can misread documents, misclassify information or generate incomplete analysis. Strong verification processes are essential.
Competing with established providers
Large technology companies and established financial software providers already have relationships with banks and lending institutions.
Demonstrating long-term value
Early productivity improvements must translate into measurable commercial benefits. Customers need to see that the platform remains useful as their workloads and requirements change.
Maintaining human accountability
Automated analysis should support responsible credit decisions, not obscure who is accountable for them.
The company’s ability to address these issues will influence whether its technology can become a standard part of commercial lending workflows.
The Future of AI in Commercial Lending
The financial services industry is moving towards more connected and data-driven operations.
AI systems can help organisations process information, identify patterns and automate repetitive activities. In lending, these capabilities could affect everything from the first application document to the monitoring of an existing loan.
Future commercial credit platforms may combine document intelligence, financial analysis, cash-flow monitoring, risk indicators and workflow automation.
Rather than treating underwriting as a single isolated activity, lenders could use connected systems to maintain a more continuous understanding of a borrower’s financial position.
This could make it easier to identify emerging risks and prepare reviews when important changes occur.
However, the development of AI in lending must remain closely connected to transparency and accountability.
Businesses need access to fair lending processes, and lenders need to understand the basis for their decisions.
The most successful systems are likely to be those that improve efficiency without weakening these principles.
Crediflow’s approach reflects this broader direction: automate the preparation of credit information while leaving important lending judgement with qualified professionals.
Conclusion: A Funding Boost for the Future of Commercial Lending 🚀
Crediflow AI’s reported £1.5 million funding round, equivalent to approximately €1.8 million, marks a significant development for the Manchester-associated fintech company.
With investment led by PXN Ventures through the Northern Powerhouse Investment Fund II, alongside Haatch and angel investors, the company plans to expand its AI-powered commercial lending platform.
Its technology focuses on automating tasks such as document collection, financial spreading, bank statement analysis and credit memo preparation.
These are important activities because commercial lending still involves substantial amounts of manual paperwork and financial data processing.
By connecting these workflows, Crediflow aims to help lenders prepare credit assessments faster and give analysts more time to concentrate on risk and decision-making.
The company still needs to demonstrate sustained performance, secure adoption and measurable value as it grows. Its technology must also meet the demanding standards of financial institutions.
Nevertheless, the funding highlights a wider trend: artificial intelligence is increasingly being applied to the operational foundations of banking, not just customer-facing applications.
If Crediflow can turn its early momentum into reliable enterprise adoption, it could become an interesting player in the evolving market for AI-powered commercial credit infrastructure. 💼🤖
Frequently Asked Questions (FAQs)
What is Crediflow AI?
Crediflow AI is a UK fintech company developing artificial intelligence software for commercial lending. Its platform is designed to automate document processing, financial analysis, credit memo preparation and other lending workflows.
How much funding has Crediflow AI raised?
Dealroom reported that the company raised £1.5 million, equivalent to approximately €1.8 million, in a funding round announced on November 3, 2026. Dealroom News
Who led Crediflow AI’s funding round?
PXN Ventures led the round through the Northern Powerhouse Investment Fund II. Haatch and angel investors also participated.
Who founded Crediflow AI?
The funding report identifies Drey Kenfack as the company’s founder. It describes his previous senior credit roles at Ford Credit Bank and DF Capital Bank. Dealroom News
What will Crediflow AI use the funding for?
The company plans to develop its platform, recruit engineers and product specialists, and extend automation into loan origination and ongoing portfolio monitoring.
What is FlowSpread?
FlowSpread is Crediflow’s financial-spreading product. It is designed to extract and standardise financial information from documents such as PDFs, tax returns and bank statements.
Does Crediflow AI replace human loan underwriters?
No. The funding report says the platform prepares analysis for credit professionals rather than making lending decisions or replacing underwriters.
How can AI improve commercial loan processing?
AI can help collect documents, extract financial figures, organise data, analyse transactions and prepare credit reports. This can reduce repetitive work while allowing credit professionals to focus on risk assessment.
Who could benefit from Crediflow’s platform?
Potential users include commercial banks, specialist lenders, asset finance providers, private credit firms and other organisations involved in business lending.